Insurance Chatbot: Answering Policy and Claims Questions Safely
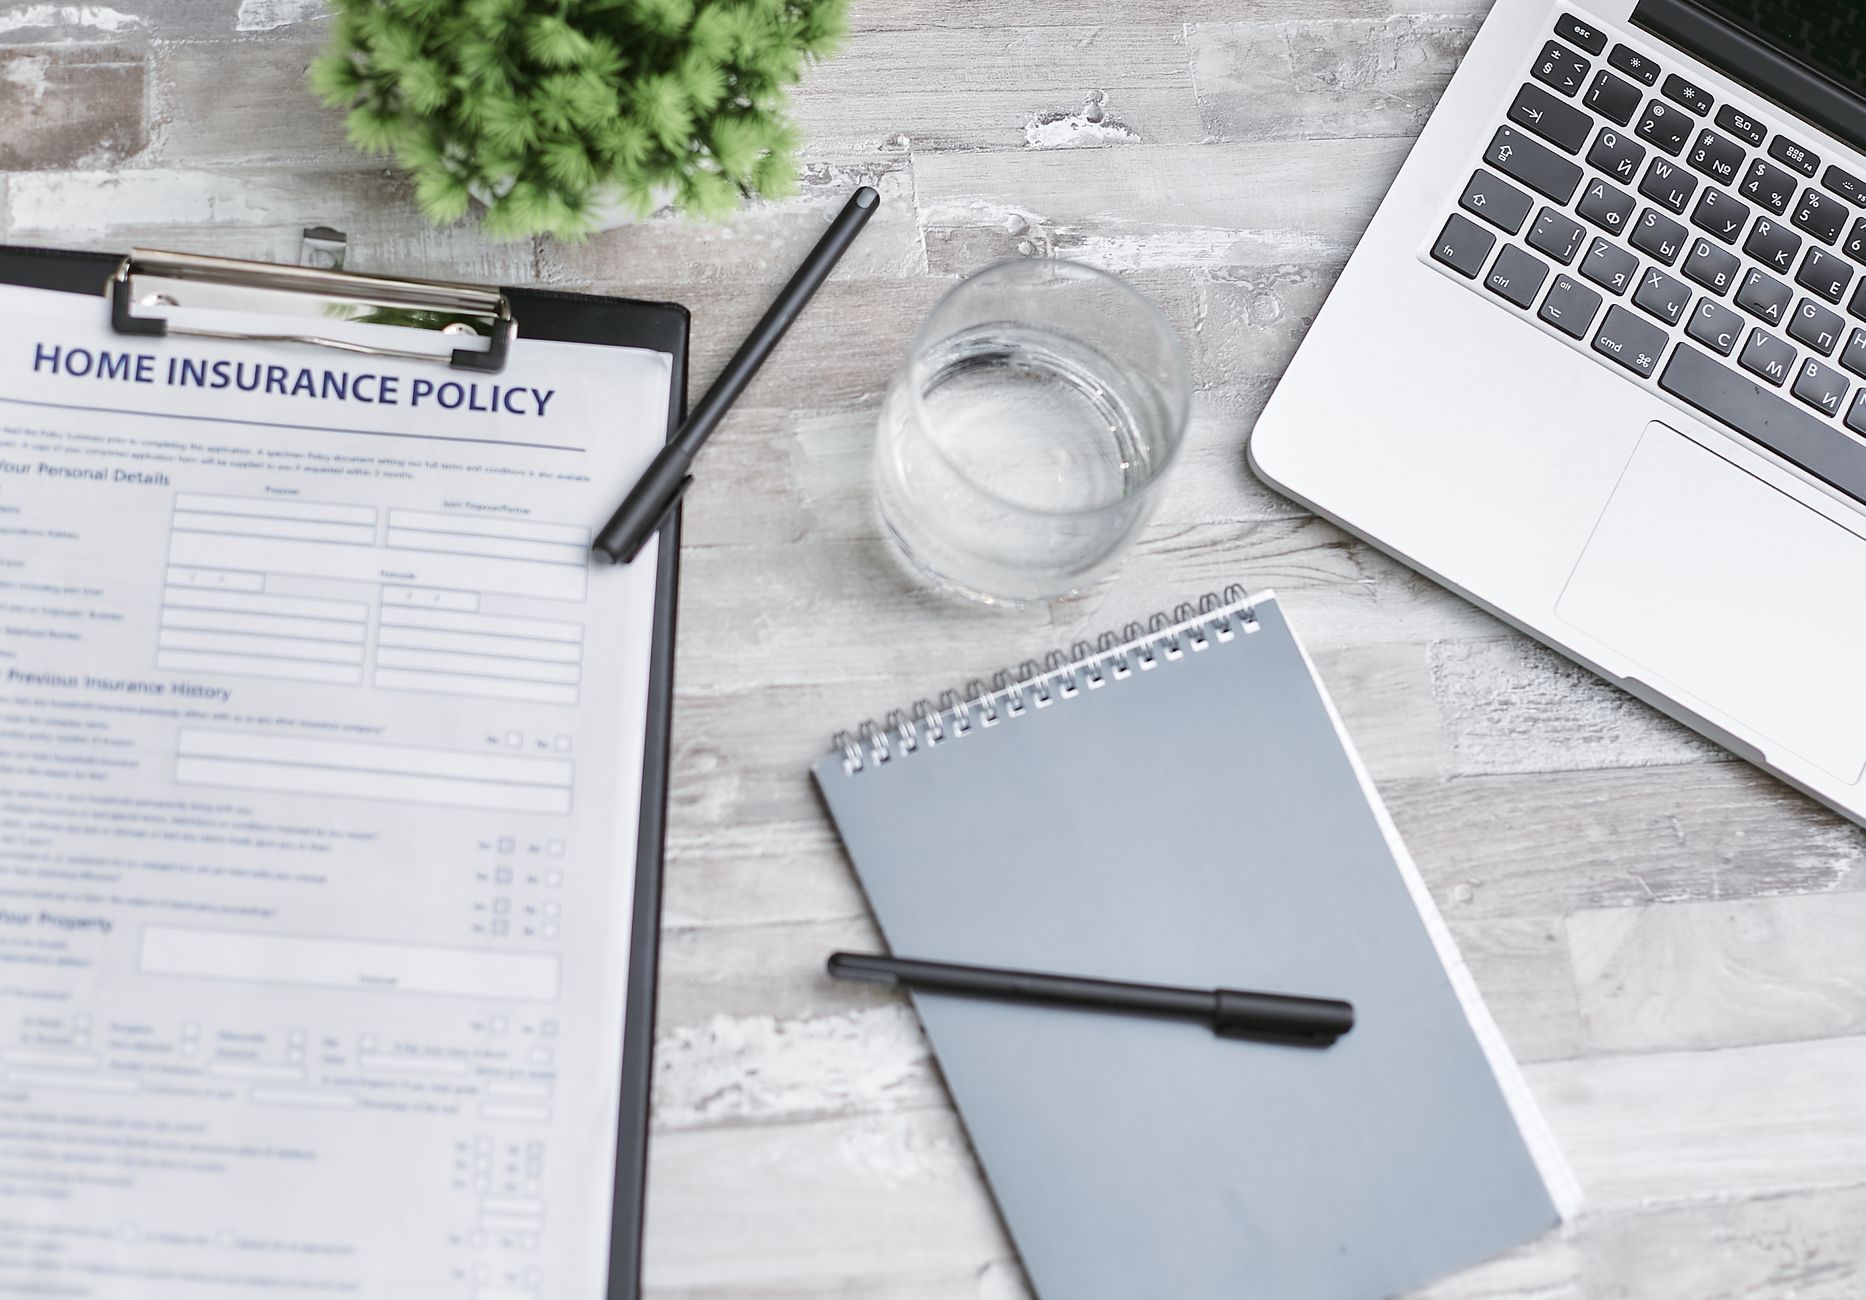
An insurance chatbot on a small agency or broker website can safely handle the repeat factual questions: how to report a claim, which documents to send, office hours, what a policy term means. It stays safe as long as it answers only from the firm’s own approved documents and never recommends a policy or judges cover. Staff answer the same calls and emails every day, and owners worry that a bot might drift into advice it has no right to give. Below: which questions to automate, where the legal line sits, and how to set up and launch the bot.
What Customers Ask an Insurance Office (and Which Questions an Insurance Chatbot Can Take)
A chatbot for an insurance agency can answer the factual questions that repeat week after week, straight from the firm’s own documents. Typical service and insurance claims questions that suit a bot:
- where and how to report a claim with each insurer the office works with,
- which documents a claim usually requires, such as photos, invoices or a police report,
- how to change an address, phone number or email on file,
- what terms like excess or deductible mean, as defined in the firm’s own documents,
- office hours, address and contact channels.
The second group is different: which policy to buy, whether a specific loss is covered, how two products compare. Those need a licensed person. Side by side, the two lists are practical insurance chatbot examples of in-scope and out-of-scope requests.
Where the Line Is: Information Versus Insurance Distribution
The line runs between giving factual information and helping a customer choose or conclude a contract, which EU law calls distribution. In the Insurance Distribution Directive text, Article 2(1)(1) says distribution includes “the provision of information concerning one or more insurance contracts in accordance with criteria selected by customers through a website or other media and the compilation of an insurance product ranking list, including price and product comparison”. Article 20(1) adds that before the contract, the distributor “shall specify, on the basis of information obtained from the customer, the demands and the needs of that customer”.
An insurance AI chatbot that asks about needs and then suggests or ranks products is doing distribution work, which puts it inside the firm’s compliance process. The safer scope is factual information from your own documents, with no recommendations and no cover decisions. National rules and the insurer’s terms apply on top of that, and this article isn’t legal advice.
What Goes Into the Knowledge Base (and What Stays Out)
The knowledge base should hold approved, general documents and nothing else. Good first entries:
- claim reporting steps for each insurer,
- document checklists for common claim types,
- a glossary of terms as the firm defines them,
- links to each insurer’s own claim forms.
Individual policy data, drafts, internal notes and anything nobody in the office has signed off stay out. Botino builds answers from your knowledge base using the company’s documents, guides and FAQs, and when that material has no answer, it says so plainly instead of making one up.
Scope Rules: How an Insurance Broker Chatbot Says No
A good refusal names the limit and points the customer to a person. If someone asks whether a loss is covered or which policy suits them, an insurance broker chatbot should say it can’t judge cover or recommend products, and then show the office phone number, email or contact form. Sample wording: “I can’t assess whether this loss is covered or suggest a policy. Our advisers can help: call the office during opening hours or send us a message through the contact form.”
Use the same wording for every cover or product question, so staff know what the customer has already heard.
Privacy: Keep Policy Numbers and Claim Details Out of the Chat
The bot should never ask for policy numbers, health details or claim specifics. It doesn’t need them for general questions. For anything case-specific, the website and the bot should show who to contact in the office. Conversations travel over encrypted HTTPS connections, but the cleanest protection is not collecting personal data in the chat at all.
How to Launch and Improve the Bot
A workable launch sequence:
- Collect real questions from emails and phone notes over a few weeks.
- Load the approved documents into the knowledge base.
- Ask the bot those questions and check every answer against its source.
- Test refusals on cover and product questions until the wording is consistent.
- Add the widget to the site with a single script.
- Review unanswered questions regularly and update the documents.
To see how answers drawn from supplied materials behave, you can try the demo assistants, including a health information assistant that answers coverage-rule questions from its own materials. Spoken answers on the website come with the Professional plan, and the offer page lists plans and monthly token limits if you want to compare options.
A well-scoped insurance chatbot takes the repeat factual questions off your staff, while licensed people keep advice and cover decisions. Start with the claim reporting steps and the glossary, keep the documents current, and let the unanswered questions tell you what to add next.
FAQ
Can an insurance chatbot tell a customer whether a claim is covered?
No, cover decisions belong to licensed staff and the insurer. The bot can explain how to report the claim and which documents to prepare, then point the customer to the office contact details.
Is a chatbot that compares insurance products allowed?
Comparing or ranking products by criteria the customer picks falls within the IDD definition of insurance distribution. A bot like that belongs inside the firm’s compliance process. Check your national rules.
What should a small agency put in the bot’s knowledge base first?
Claim reporting steps, document checklists, a glossary of terms and office details. These are easy to verify before an insurance chatbot goes live.
Related posts
Car Dealership Chatbot: Stock, Warranty and Trade-In Questions
A car dealership chatbot can take the repeat questions off your hands: opening hours, test drives, financing documents, trade-ins, warranty, delivery. It…
Salon Chatbot: Answering Price, Treatment and Aftercare Questions
A salon chatbot on your website answers the routine questions about prices, treatment length, preparation and aftercare, and it does that from…
Chatbot for Membership Organizations: Renewals, Events, Benefits
A chatbot for membership organizations answers the general questions people keep asking about joining, fees, renewals, benefits and events. It works from…